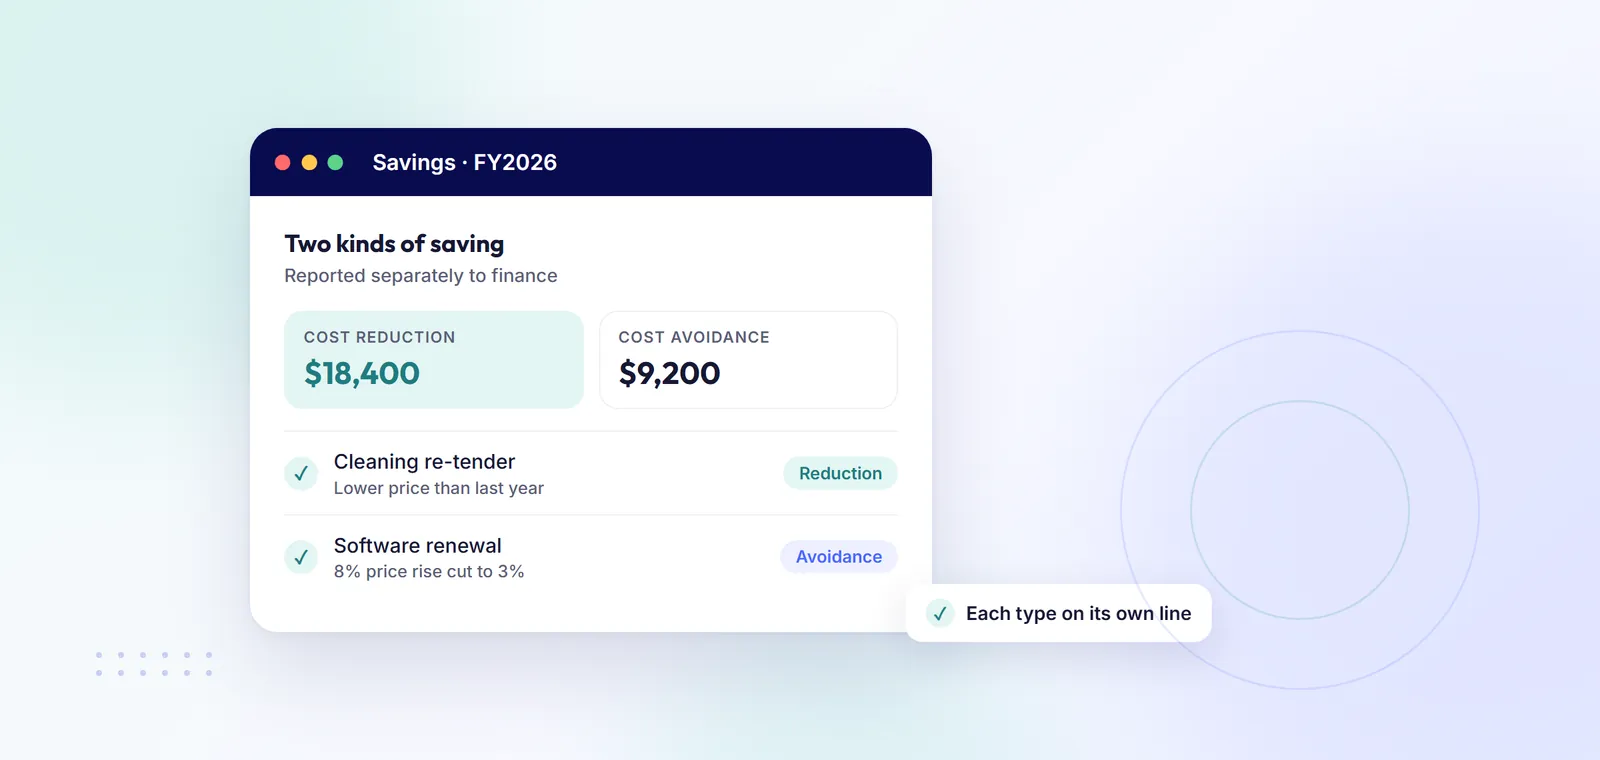
Cost reduction means paying less than you paid before, so it shows up as a lower number in your budget and P&L. Cost avoidance means not paying more than you otherwise would have, for example stopping a supplier's price rise. It stops a cost going up, but it does not reduce the budget. Both count as procurement savings, so report both, on separate lines and each against an agreed baseline.
Put simply, cost avoidance is preventive: it stops future price increases before they reach your costs. Cost reduction lowers costs you already have. Cost reduction is also called cost savings or hard savings. Cost avoidance is often called a soft saving.
| Cost reduction | Cost avoidance | |
|---|---|---|
| Definition | Paying less than you paid before for the same thing | Not paying more than you otherwise would have |
| Example | Retendering a contract and getting a lower annual price | Stopping a supplier's price rise at renewal, or buying something new below the quoted price |
| Baseline | The price you actually paid last time | The price you would have paid: the supplier's proposed price, or the quote |
| Shows in the budget? | Yes. Next year's budget line can go down | No. Spend stays the same or still rises, just by less |
| How finance usually treats it | A hard saving that can come out of the budget | Reported, often as a soft saving, but not taken out of the budget |
| How to evidence it | The old and new contract prices, and the volumes you bought | The supplier's written price rise or quote, and the final agreed price |
These examples use simple, made-up numbers.
You pay $50,000 a year for office cleaning. You retender it, and the new contract for the same scope costs $44,000 a year.
Finance can take $6,000 off next year's cleaning budget. This is the saving a CFO can see in the P&L.
Your IT support contract costs $30,000 a year. At renewal, the supplier writes to say the price will go up 8%, to $32,400. You push back and agree a 3% rise, to $30,900.
Your spend still goes up by $900, so nothing comes off the budget. If you had held the price at $30,000, the full $2,400 would be cost avoidance, and there would still be no cost reduction. Price rises often arrive with automatic renewals, so track the notice date as well as the end date.
You need 200 laptops for a new team. You have never bought them before, so there is no previous price. The quotes average $1,100 a laptop, and you negotiate $1,000.
There was no existing budget line to reduce, so this is cost avoidance, although some teams call it a negotiated saving. Agree the label and the baseline quote (first, average or highest) with finance, then use the same method every time. Our guide to cost avoidance in procurement has more examples.
For a longer list, see our guide to types of procurement savings.
Finance stops trusting procurement numbers when the two are added into one figure. Instead:
A spreadsheet works for a handful of savings, and our free procurement savings tracker is a simple place to start. Once several people log savings, savings tracking software helps stop double counting. For a step-by-step method, see our guide to reporting savings to the CFO.
oboloo is free-forever procurement software for SMEs and charities. You can track procurement savings with unlimited savings initiatives on the free plan, and record each one by type: cost avoidance (such as stopping a price rise), hard savings (such as negotiating a lower price) and process savings (reducing hours). The baseline, assumptions, timing and owner are recorded upfront.
Savings validation can be done by procurement, finance or both together, and only validated savings make it into reports. Savings move to realised when their milestones are hit, and dashboards keep pipeline, projected and validated savings apart. You can report by project, team, supplier and timeline. Validation is in the free plan. The paid Savings Plus plan adds savings approvals.
Yes. It is money you did not have to spend. It does not lower the budget, though, so report it separately from cost reduction and agree the baseline with finance first.
No. The P&L shows what you spent, and avoided spend never happened, so it does not appear there. That is why cost avoidance needs its own line in your savings report.
Take the price you would have paid (the supplier's proposed price or the quote) and subtract the price you agreed. Multiply by the quantity or the contract period. A renewal proposed at $32,400 and agreed at $30,900 is $1,500 a year of cost avoidance. As a percentage, divide the avoided amount by the price you would have paid: here, about 4.6%.
A hard saving lowers spend against what you paid before, so it shows in the budget. A soft saving is real value that does not reduce the budget, such as cost avoidance or hours saved.
On separate lines for cost reduction, cost avoidance and process savings. Give each saving a baseline agreed with finance, have it validated, and split forecast savings from realised ones.